| MARKET OUTLOOK |
As on 30th September 2026
|
Equity market
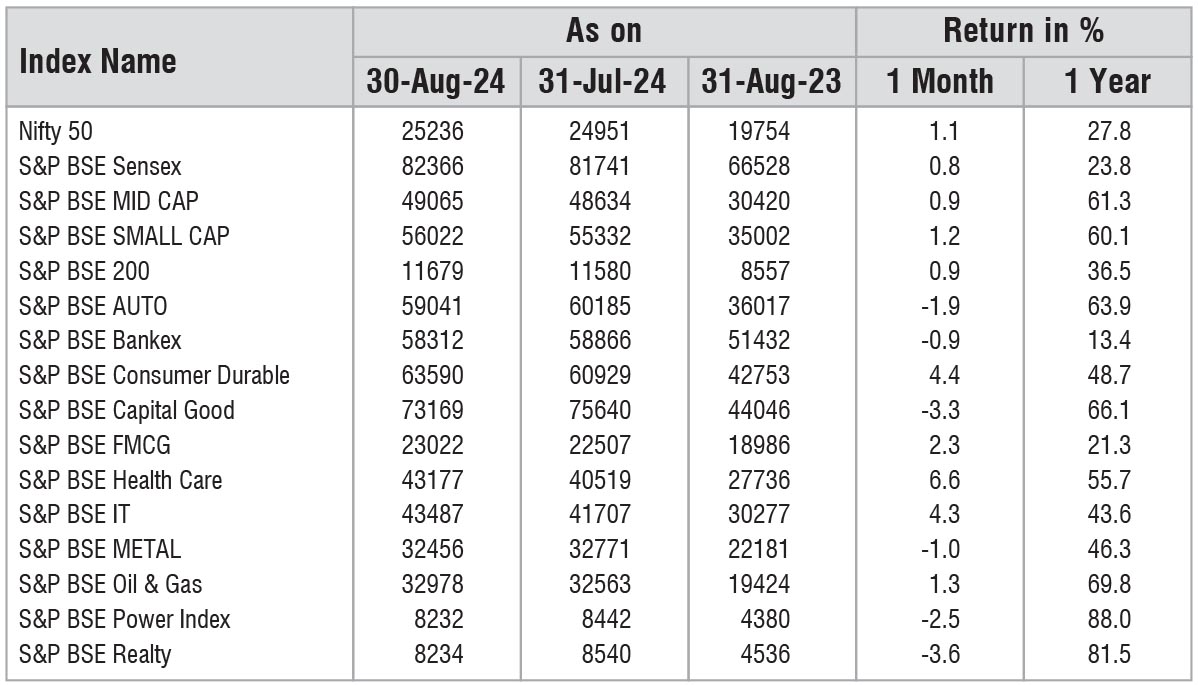
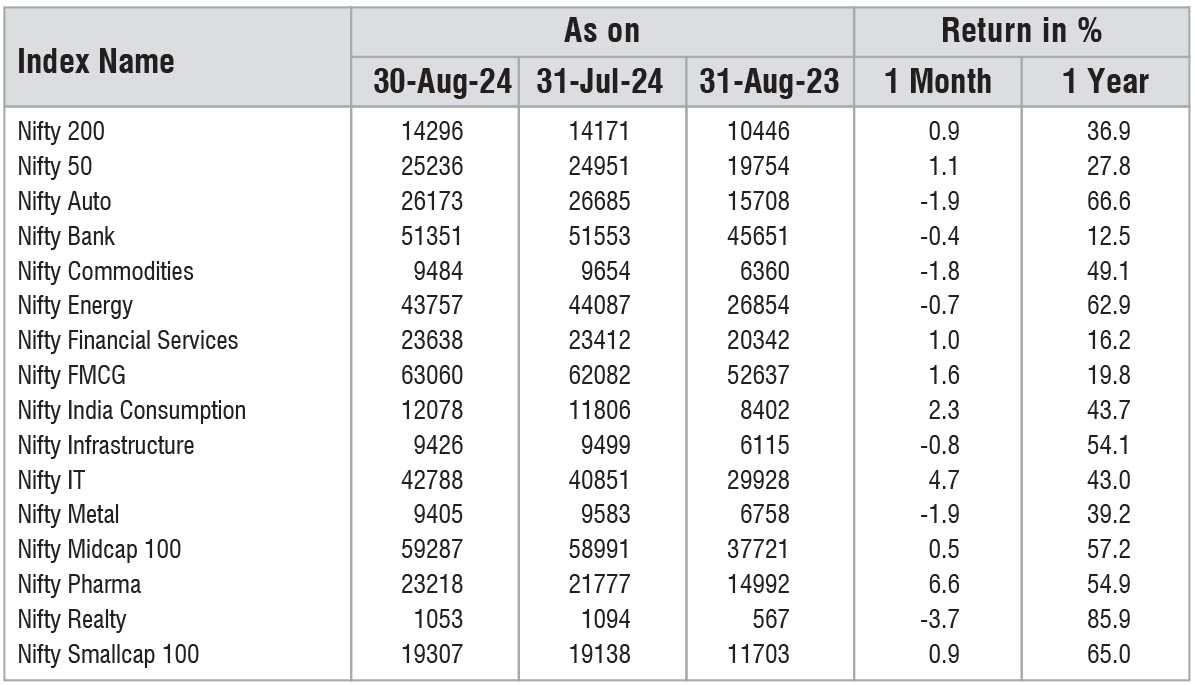
BSE Sensex and NSE Nifty corrected sharply during the month with the broader market performing better than the large cap indices.High energy prices and global logistical challenges on the back of West Asia Conflict have been the key points of concern. India business activity remains robust and corporate commentary on earnings growth potential continues to point towards a strong year FY27.
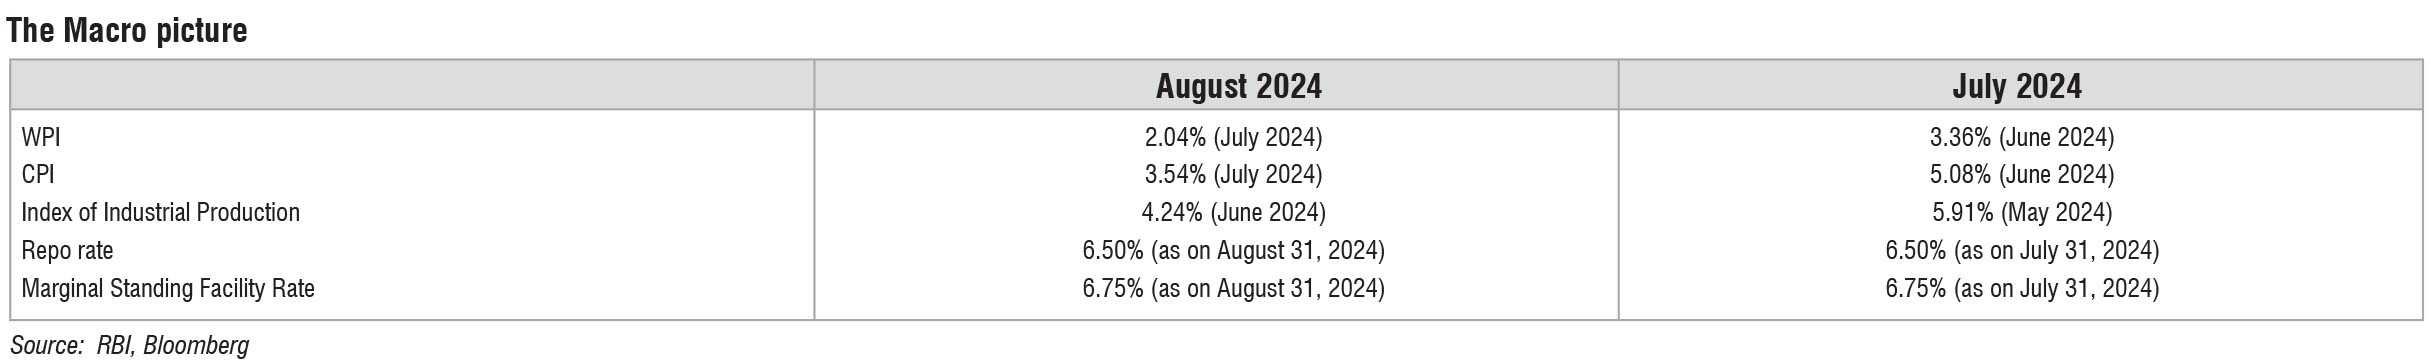
Inflation
India’s Wholesale Price Inflation (WPI) Index came in at 9.92% YoY during the current month as compared to 9.78% for the previous month on account of sharp rise in fuel, increase in food and commodity prices. Incrementally we expect WPI to remain on the higher side on account of higher commodity and food prices.
Aug-26 headline inflation rose to 4.82%, driven by higher food inflation (5.95%), while core inflation also ticked up to 4.2%. Food price momentum dipped and was largely driven by sugar (~8% mom), while other categories remained relatively subdued. The uptick in core inflation was driven by higher gold and silver jewelry prices; however, momentum in other core inflation categories also picked up, with core CPI ex-precious metals at 2.9% (vs 2.7% prior).
Q1FY27 GDP growth came at a strong 7.8% led by exports and investments. Exports grew 12%, investments at 11.9%, private consumption at 7.1% while government consumption grew by 4.3%.
Other macro developments (fiscal deficit and household savings)
4QFY26 CAD came in with a surplus of USD7bn against a deficit of US$13.2bn in 3QFY26 (1.3% of GDP), mainly due to healthy net services exports US$28bn and higher invisibles $20bn.
FY26 fiscal deficit stood at 4.4%, and the government had given a target to achieve 4.3% for FY27E. With crude spike post the west Asia conflict, there were concerns on achievement of these targets. However recent correction in Crude prices does make these assumptions possible to deliver.
FY26 net household financial savings rate stood at 7% of GDP (6% for FY25 and 5.3% for FY24). The same ratio had moved higher during the pandemic period to 12% in FY21 compared to 7.7% in FY20.
Market Outlook:
Corporate earnings growth as per Bloomberg consensus stands at healthy mid-teens for FY27 and FY28. Over the past two years India equity markets have consolidated in a range and FY27 is turning out to be another year of time correction so far. Valuations specially for the large cap universe i.e. the top 100 stocks in terms of market capitalization have normalized significantly and NSE Nifty 50/BSE Sensex 30 indices trade at or slightly below average valuations on a 1 year forward earnings estimates.
Our interactions with corporate India over the recent past make us believe that earnings downgrade risk is much lower even with global challenges ongoing like the West Asia Conflict and we are increasingly more constructive on the risk reward presented by the current market levels. Infact, selectively we do come across businesses where prospect of earnings growth of >30% CAGR is quite high and given the time correction in the markets a few names valuations make it quite appealing for the long term.
Over the past 20+ years of covering Indian businesses we are enthused with select manufacturing companies for example Auto Ancillaries/Capital goods/Industrials where it’s common to hear management talking of cost competitiveness globally even relative to China and the potential to gradually increase market share not only in India but also developed world like US, EU, Asia etc. We are also increasingly seeing early benefits of R&D efforts being put in by select companies. In the past technical tie ups with global companies were the only way to enter new businesses or geographies. Now some companies are starting to develop their own technology platform to capture global markets. As of now R&D is restricted to select leading players in some sectors but a good beginning has been made and we are optimistic of this trend catching up across businesses in the mid to long term.
We in our portfolios are focused on companies which can grow earnings at a fast pace and most importantly balance sheets/cash flow being on the positive side with less leverage.
Long-term structural drivers like demographic advantage, low household debt, limited penetration across different consumer categories, increased potential for financial savings and urbanization makes India a compelling equity story from medium to long term perspective.
We believe investors would be well advised to invest with medium to long term perspective and systematically increase exposure to Indian equity markets.
Disclaimer: The views expressed are in no way trying to predict the markets or to time them. The views expressed are for information purpose only and do not construe to be any investment, legal or taxation advice.
Please consult your Financial/Investment Adviser before investing. The views expressed may not reflect in the scheme portfolios of Tata Mutual Fund. This note has been prepared using information believed to be
accurate at the time of its use.